Inheritance Tax Planning: How Integrated Retirement Communities Can Help Protect Your Family’s Future
Piece by LMS Retirement Living CEO, Karl Hallows.
Recent research suggests that moving into an integrated retirement community like Castle View Windsor, which offers deferred fee options, could help you reduce your inheritance tax (IHT) bills and give your family greater peace of mind
Understanding the Challenge
Data from estate agency Savills shows that older people now hold £2.95 trillion in housing wealth across the UK. With inheritance tax due to come into the scope of pensions from 2027, many more families will face significant tax bills when a loved one passes away.
Although not suitable for everyone, a growing number of retirees are exploring how moving into an integrated retirement community – and choosing to defer their fees – can provide meaningful financial benefits for their families.
What Are Integrated Retirement Communities?
Integrated Retirement Communities (IRCs), such as Castle View Windsor, offer self-contained homes for sale or rent. They include 24-hour on-site staff and typically feature a restaurant, leisure option, activities schedule, and optional care services
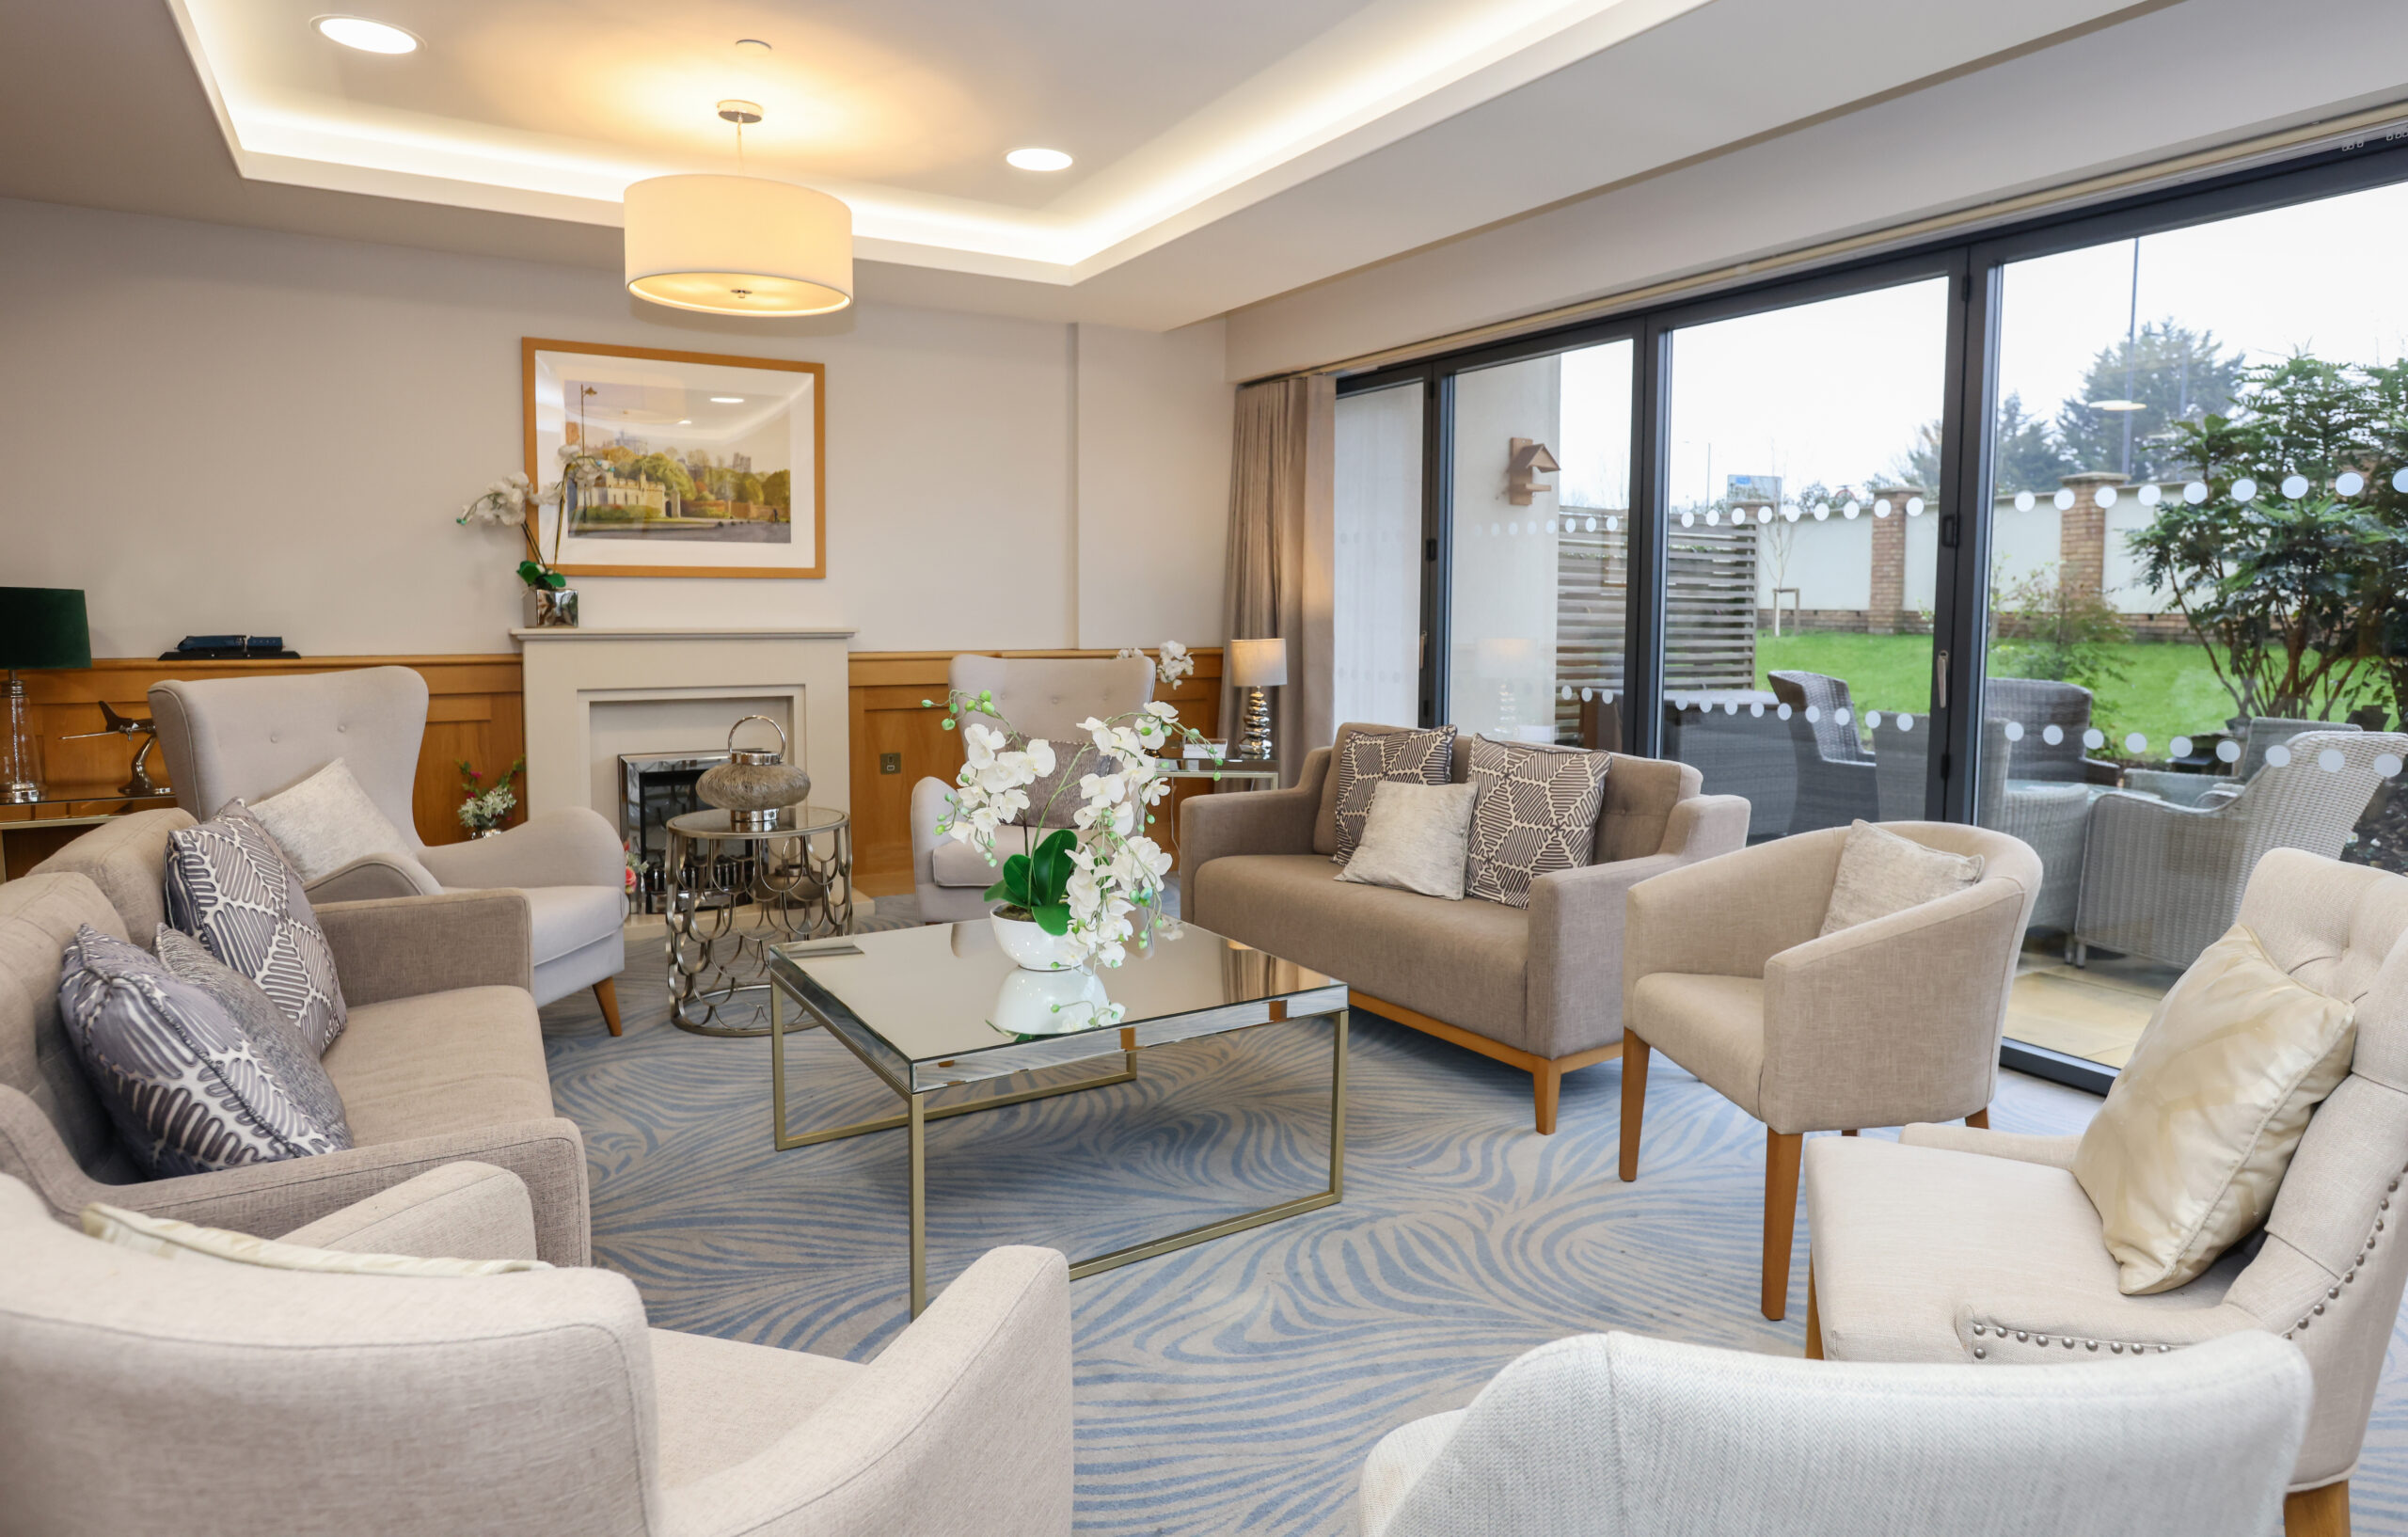
At Castle View Windsor, our community combines spacious apartments with the security of 24/7 on-site support, beautiful communal spaces, landscape gardens and a vibrant social environment – all nestled in the heart of Windsor.
What is a Deferred Management Fee
In UK retirement living communities (sometimes called retirement villages or retirement living developments), a Deferred Management Fee (DMF) — also called an exit fee — is a charge you pay when you sell or transfer your property, not while you’re living there. It’s effectively a way of sharing the ongoing costs of running, maintaining and improving the community over time.
What the Deferred Management Fee (DMF) Covers
Here’s what these deferred fees typically cover:
- Long-term maintenance of the community
DMFs help fund future major repairs and upkeep — things that aren’t part of everyday running costs but are essential over many years, like roof work, lift replacement, structural works, or resurfacing roads and paths. This reduces the risk of sudden large bills later on.
- Refurbishment and resale costs
Part of the fee is used to prepare your property for resale — this could include decorating, essential works and marketing costs paid by the operator.
- Communal facilities and shared infrastructure
Community features such as lounges, gardens, gyms, cafés, security systems, and other shared amenities all need ongoing investment and renewal. The DMF contributes to keeping these in good condition for future residents.
- Management and administrative support over time
Beyond everyday service charges, DMFs help cover the long-term commitment of managing the village or development — ensuring someone is responsible for compliance, future planning, health & safety and overall community governance even after you leave.
How Deferred Fees Work
When someone moves into a retirement property, the associated management fees are normally agreed upfront. However, if you choose to defer your fees, they are not paid until the property is sold, which means they do not count toward the value of your estate for IHT purposes. Only the property value itself is included in your estate.
A Practical Example
If a home is valued at £400,000 and there is a deferred fee of 20%, when an individual passes away, the estate will be valued at £320,000 (£400,000 minus 20%). This may fall below the IHT threshold, potentially saving families a substantial bill upon death.
As Chris Etherington, Tax Partner at RSM UK, explains: “It may not be appropriate for everyone but for some, it could mean they have more to spend during their lifetime and can offset the costs against other assets which might otherwise be taxable at up to 40%”.
Understanding Inheritance Tax
IHT is paid on the estate of someone who has passed away. There’s normally no tax to pay as long as the value of the estate is below £325,000. If you give away your home or “main residence” to your children, your threshold can increase to £500,000.
Although inheritance tax currently affects relatively small numbers, this is set to change for several reasons:
- The £325,000 nil-rate band threshold is frozen, so with inflation, more people will have estates larger than this amount
- From 2027, pensions will no longer be exempt from IHT, meaning many more families will be affected by potential tax bills
The Benefits Beyond Finance
What many homeowners at Castle View Windsor and other integrated retirement communities discover is that the financial advantages are just one part of the equation. The wider benefits to quality of life often surprise newcomers.
As one homeowner shared: “I didn’t feel the need to make any new friends, so the attraction of the community didn’t [initially] really pull me. Now I look back, my wife and I have made a lot of friends. And if you spoke to the homeowners, what you’ll find is people come for different reasons
At Castle View Windsor, our homeowners enjoy:
- Security and Peace of Mind – 24/7 on-site support and emergency services
- Active Community Life – Organized social events, leisure activities and cultural programs
- Better Health Outcomes – Research shows that integrated retirement community homeowners experience a 75% increase in physical activity, fewer falls, and significantly reduced feelings of isolation.
- Independence Retained – Your own home with optional support / care services available as needs change
What You Need to Know About Deferred Fees
If you’re considering a property with deferred fees, there are important steps to take:
Choose an ARCO-Approved Provider. Castle View Windsor is committed to upholding high standards. When considering any integrated retirement community, ensure it is ARCO-approved, as this provides essential consumer protection and adherence to the ARCO Consumer Code
Understand What’s Covered. ARCO warns that family members should clearly understand the deferred management fee arrangement to avoid surprises after someone has passed away. At Castle View Windsor, we provide transparent information about all fees and services.
Seek Independent Advice – It’s essential to obtain independent legal and financial advice before moving. ARCO members, including Castle View Windsor, are required to advise customers to seek this guidance when considering a move to an integrated retirement community.
Consider Your Options – Nimesh Shah, Chief Executive at Blick Rothenberg, suggests checking with the provider what the cost would be if you paid the service fee during your lifetime, rather than letting it accrue until death. He also emphasizes the importance of checking your actual estate value: “Don’t let a perceived tax benefit become a carrot to enter into these arrangements. The main point here is to calculate the value of your estate—if your estate is below the inheritance tax nil rate band, then you don’t have to pay inheritance tax”.
Making the Right Decision for Your Family
Moving to an integrated retirement community is a significant decision, and it should be driven by what’s right for you and your family’s circumstances. The potential IHT benefits can be meaningful, but they should be part of a wider financial and personal plan.
At Castle View Windsor, we’re here to help you explore whether an integrated retirement community is the right choice.
Our team can answer your questions and help you understand how our community could work for your lifestyle and financial planning.
Suggested Resources
Castle View Windsor does not provide tax or financial advice; information in this article is for general guidance only and should not be relied upon as a substitute for professional advice.
Always speak to a qualified tax adviser to understand what is appropriate for your personal circumstances.
As you explore this option further, you may find these resources helpful:
- ARCO (Association of Retirement Community Operators) – Find ARCO-approved integrated retirement communities and learn about consumer protections
- HM Revenue & Customs IHT Guide – Official government information on inheritance tax thresholds and planning
- Citizens Advice Bureau – Independent guidance on IHT and estate planning
- MoneyHelper – Free, impartial financial guidance on retirement planning
- Castle View Windsor Tours and Information – Explore our community and speak with our team about your options
Questions & Tours
Families never have to make these decisions alone; the Castle View team and our later life advisors are here to guide and support you at every stage of your journey.
Whether you would like to ask a few questions, talk through options or come and look around the community, simply contact us for a relaxed chat or to arrange a visit.
CONTACT OUR LATER LIFE ADVISERS FOR A LOOK AROUND CASTLE VIEW